Seven million Americans have Alzheimer's, and families are feeling the cost in cash flow, housing, and time.
Angela Davis, 65, moved her mother into her own home after a standard care facility did not work. She now manages medications, helps with hygiene, and monitors her mother at night. Her mother's care, plus home maintenance, costs about $7,000 a month. Her mother brings in $3,200 in monthly retirement income, and Davis covers the rest.
That kind of pressure is common. One estimate puts lifetime dementia costs at more than $400,000. Families told Business Insider they are also paying for frequent hospitalizations, physician visits, expensive medications, transportation, home modifications, power-of-attorney legal fees, and aging-in-place technology.
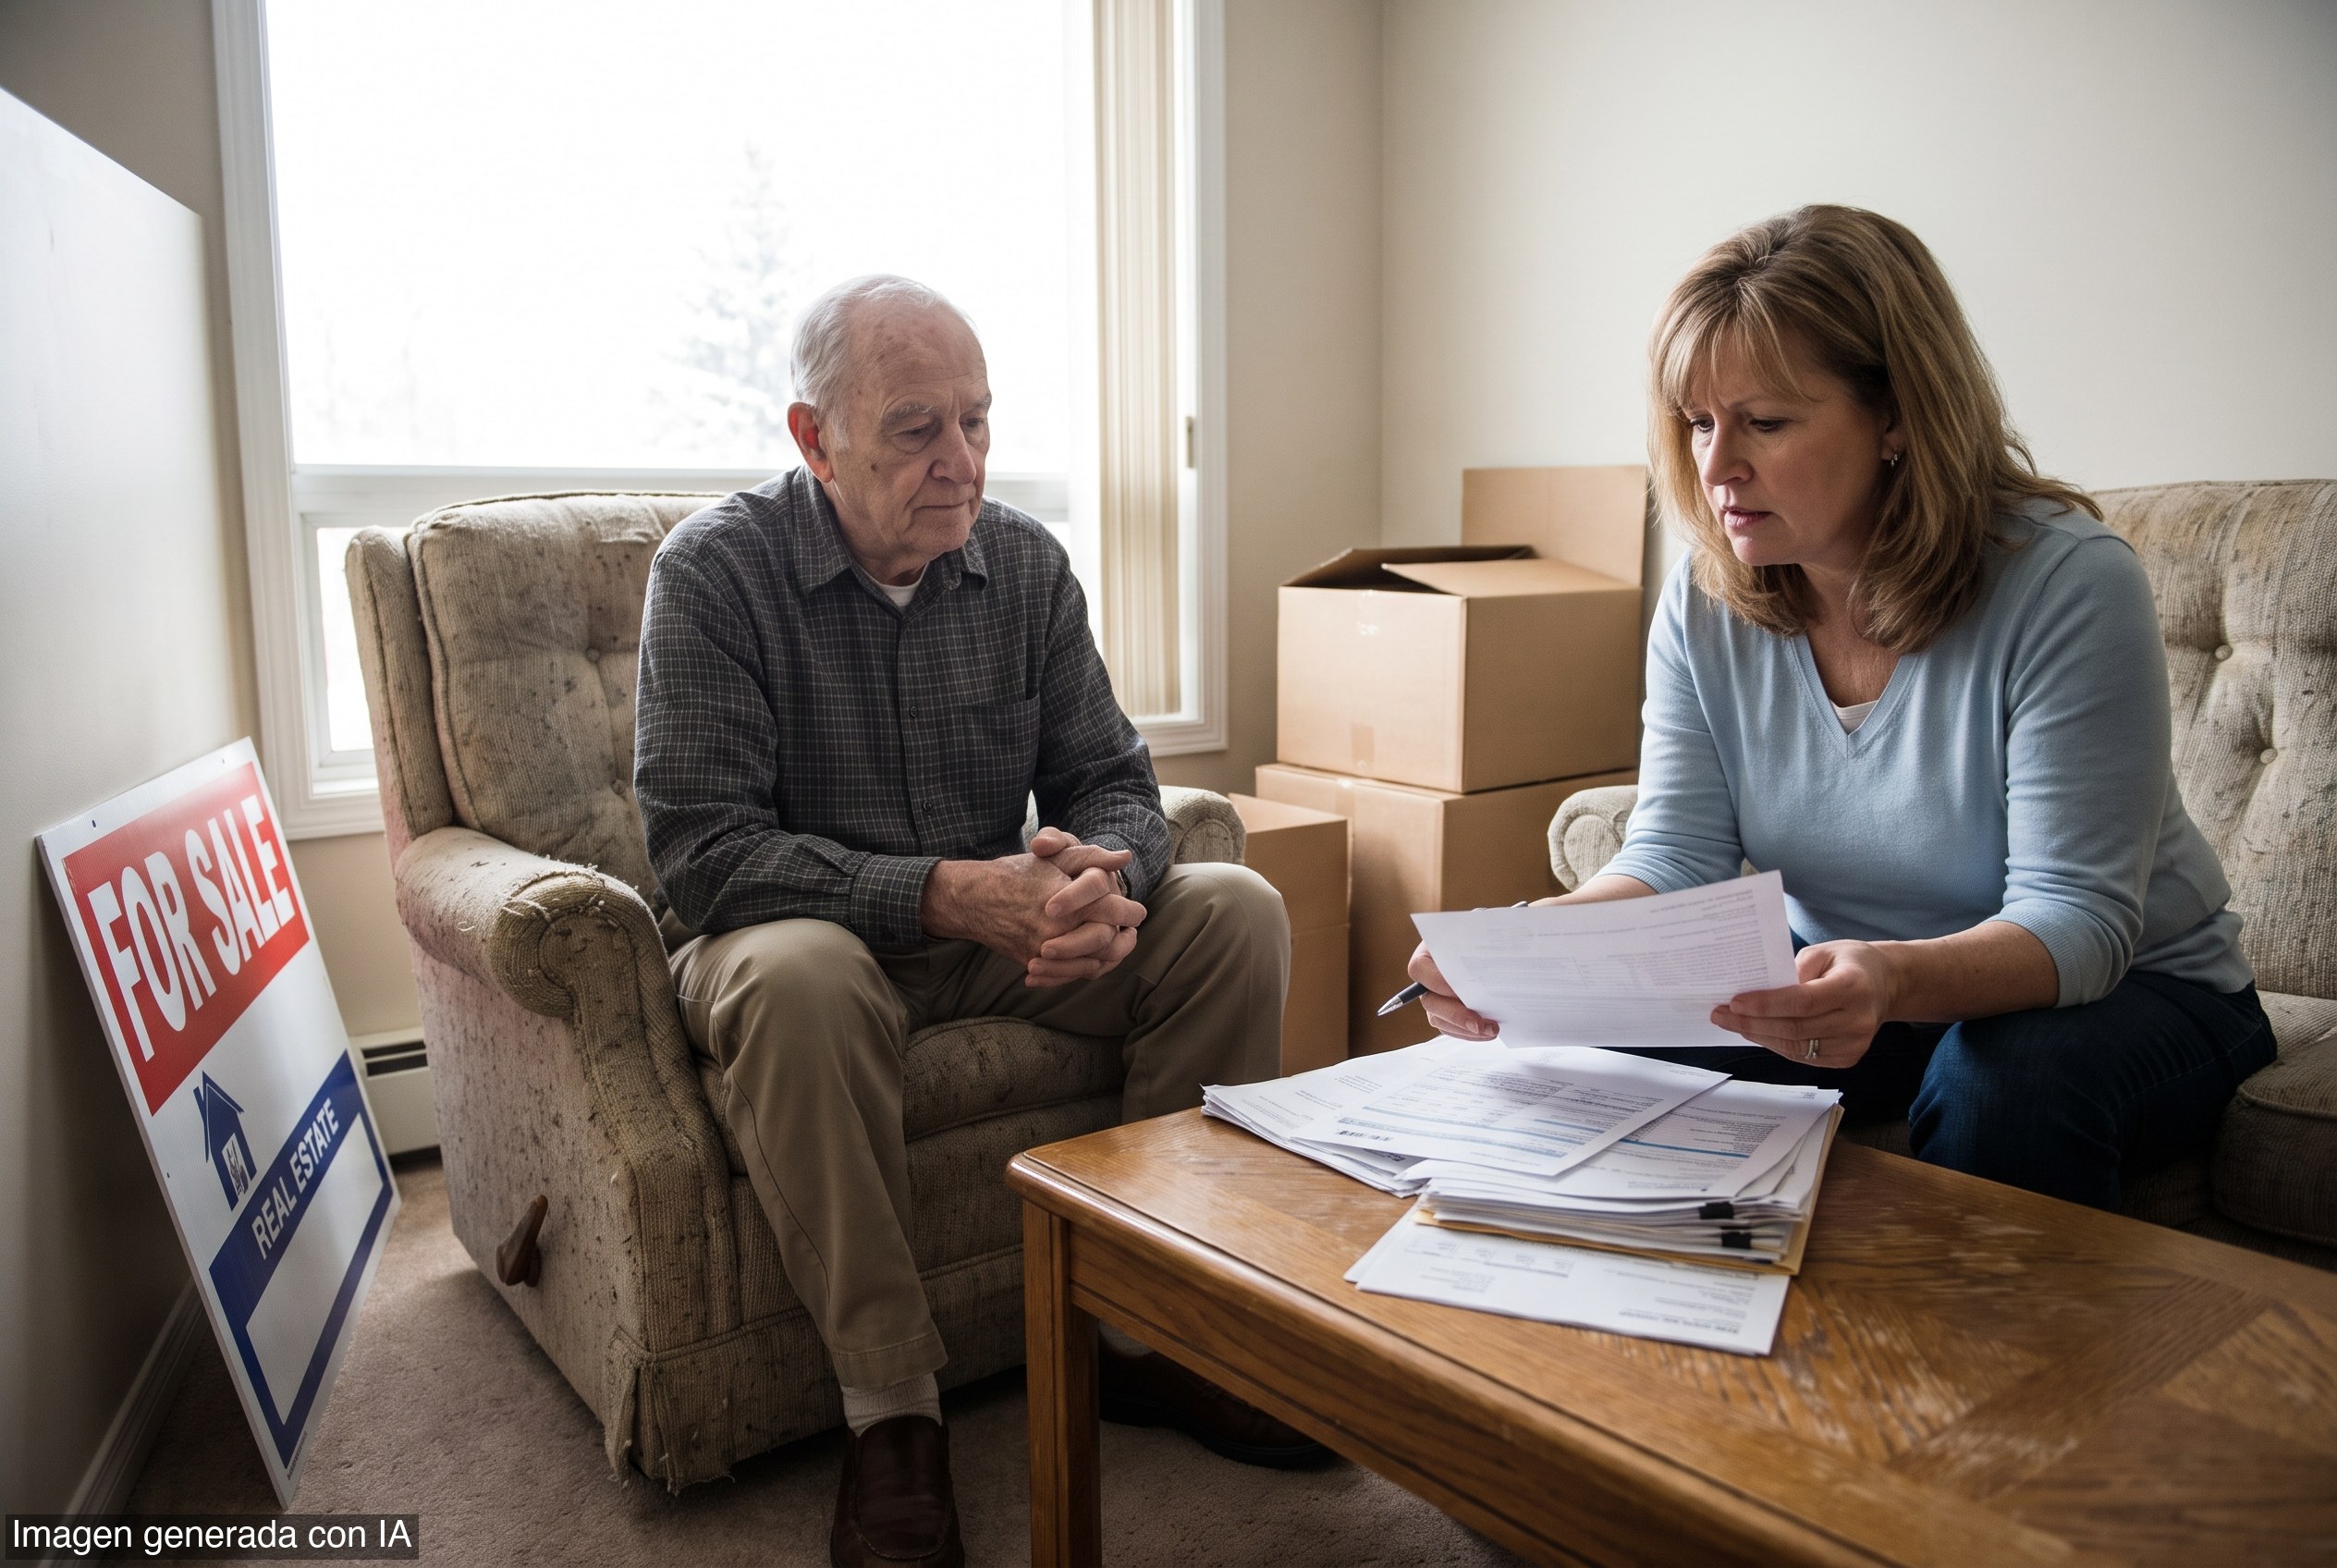
Wendy Rowland, 53, said she and her husband spent through his 401(k) and sold their house of 20 years to manage care for his early onset Lewy body dementia. He now lives in a memory care facility that costs $6,750 a month.
Keith Pavlick, 53, said his parents moved into assisted living for $9,000 a month after his father's dementia diagnosis in March 2025. He said memory care facilities in his area cost $14,000 monthly. Sharon Winterton, 53, said long-term care insurance is covering her mother's $7,000 monthly assisted living costs, which has spared her from a larger out-of-pocket hit.
The median cost of memory care is about $8,000 a month, according to data from SeniorLiving.org. Those facilities are more expensive than standard assisted living because dementia patients require 24/7 supervision by specialized caregivers, along with higher security and maintenance costs.
Medicare generally does not fund long-term memory care. Medicaid helps eligible families, and some households rely on long-term care insurance. Others pay out of pocket.
For families, the playbook is brutal: the care bill keeps coming whether income does or not. That forces hard choices about savings, homes, and work. For founders and operators, the lesson is equally clear. When a household's runway gets cut by a chronic care bill, everything else gets repriced around it.