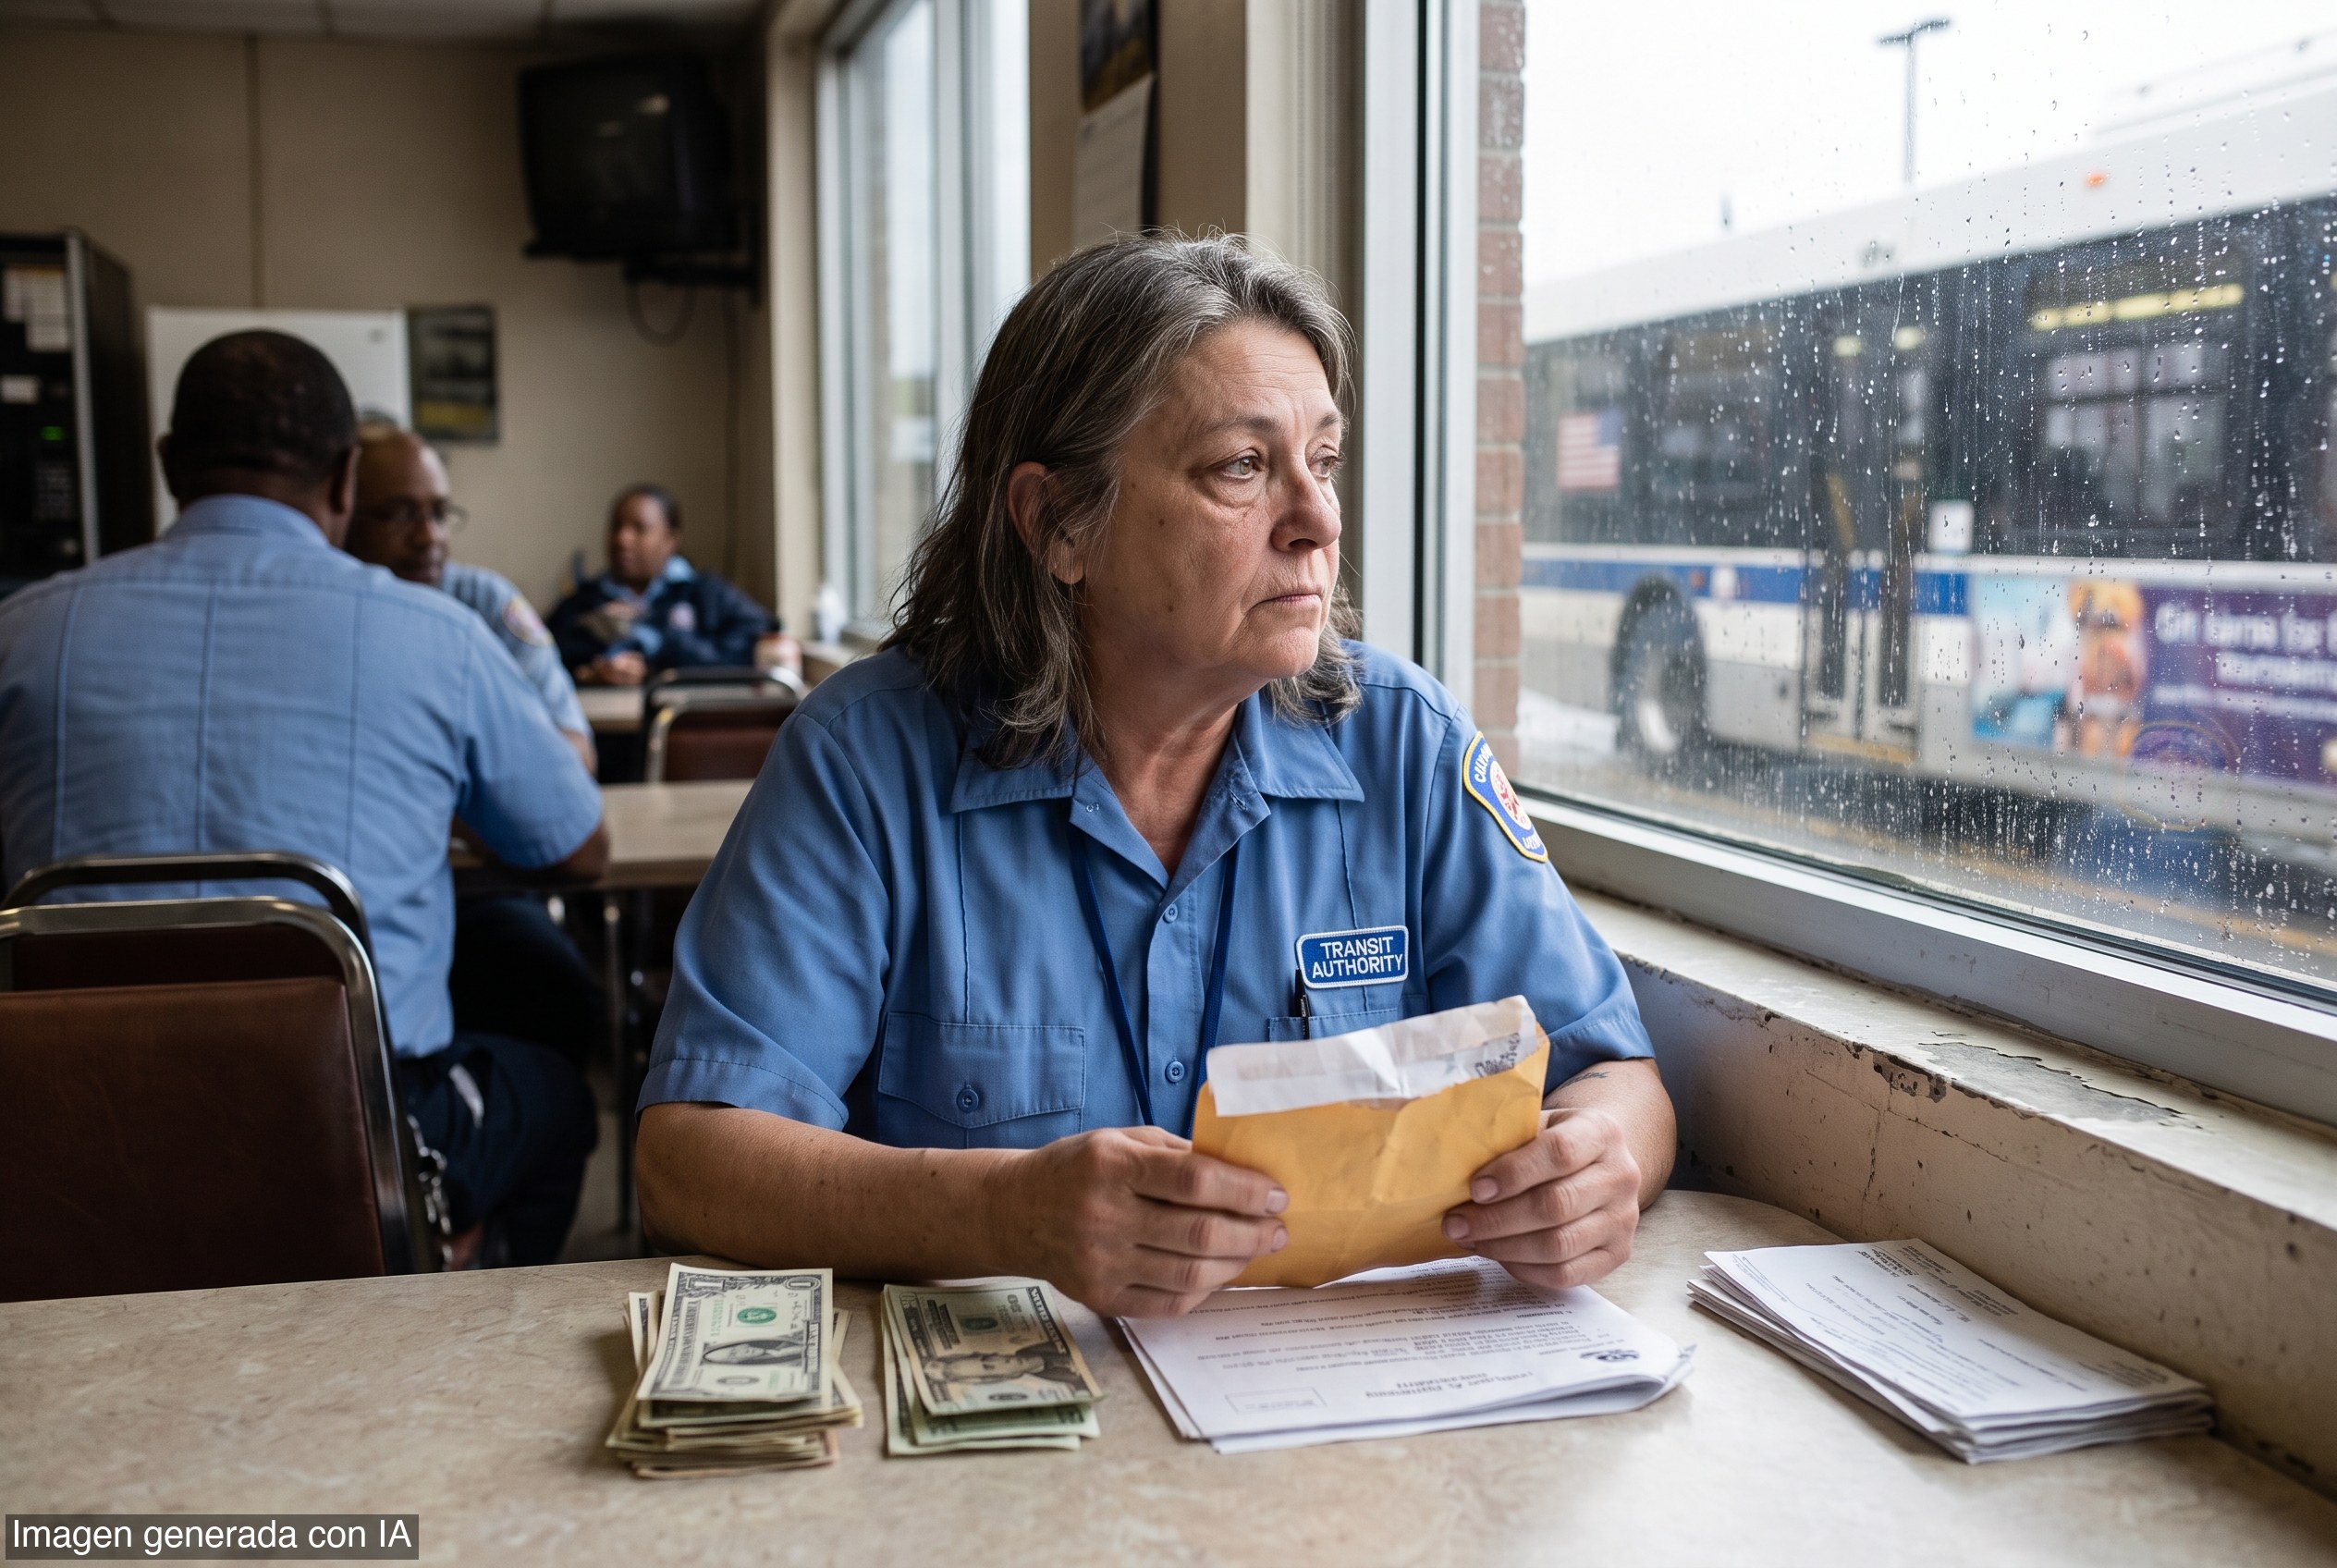
Nansi Lynch is 60 and says she is approaching retirement with a $156,000 student-loan balance.
Lynch took out federal parent PLUS loans to help both of her children get through college. Her monthly payments were $238 under an income-driven repayment plan, and she worries they will rise when her forbearance ends early next year.
She said the debt is already shaping her life choices. She wants to retire in the next five years, but says that is not possible while she is still managing student-loan payments. She also said she turned down the chance to lean on her children for help because they cannot afford it.
Lynch graduated high school and has worked as a school bus driver for nearly 30 years. She also runs classes at her gym between her morning and evening bus shifts. She said the debt has affected more than retirement: the Small Business Administration denied her a loan request to move her gym to a better location because she has too much debt in her own name, including her student loans and a mortgage.
The parent PLUS program carries the highest federal interest rate at 9.07%. Under the previous rules, parents could borrow the full cost of attendance. In July, the Trump administration imposed a lifetime borrowing cap of $65,000 per dependent for new parent PLUS loans in an attempt to address spiraling debt.
The scale of the problem is growing. Outstanding debt from parent PLUS loans increased from $62 billion in 2014 to nearly $110 billion in 2024, according to the Institute of Education Sciences.
Lynch said the open-ended borrowing was 'problematic' for her because it let her take on debt she could not afford while bringing in around $45,000 a year from bus driving. She said she wanted her children to get a better education and a better job, but the long run has left her 'stuck with all of the student-loan debt.'
The deeper lesson for founders, operators, and anyone managing a household budget is simple: debt that looks manageable in the moment can quietly consume future options. When payments rise and income stays flat, retirement, capital access, and flexibility all get squeezed.
That is the part borrowers should price in before signing. The family may mean well, but free cash flow still has to cover the bill. When it does not, the administrative state is not the one retiring late; the borrower is.