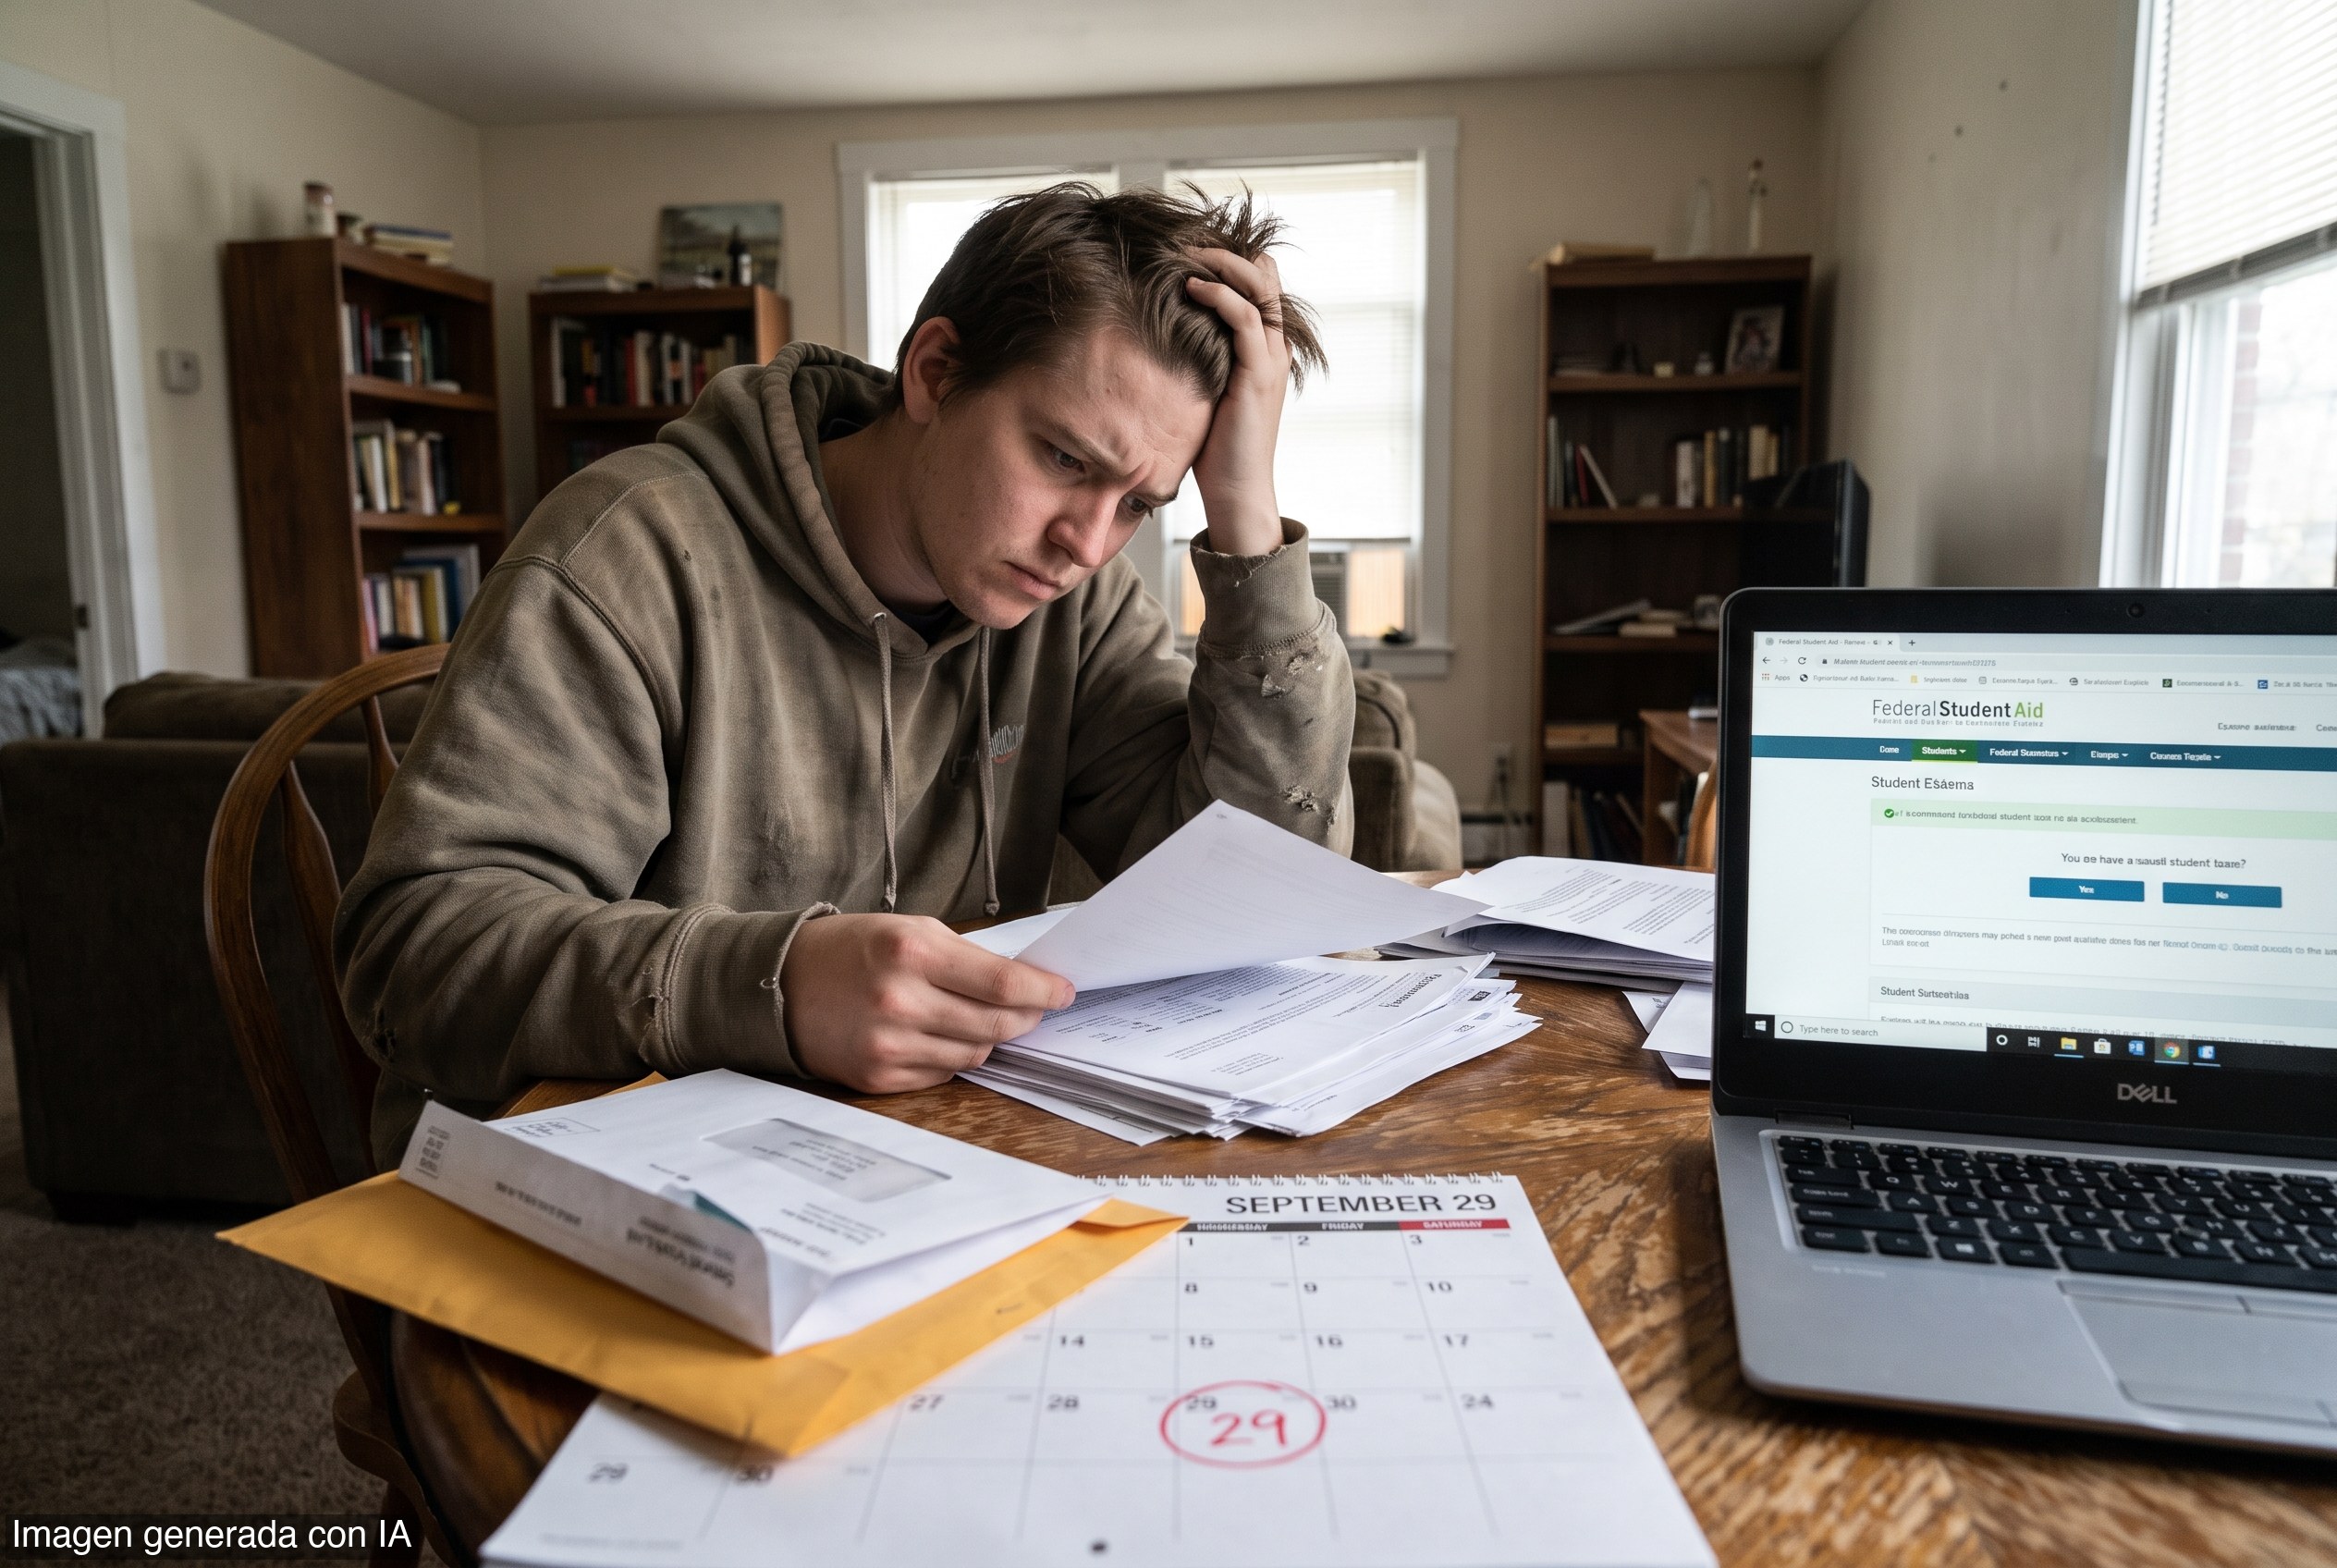
The clock is running out for the first wave of student-loan borrowers caught in the SAVE plan transition. September 29 is the initial deadline: borrowers who received their 90-day notice at the start of July must select a new repayment plan by then or be automatically moved to a standard repayment plan — the most expensive monthly-payment option available.
What happened to SAVE
The SAVE plan was a Biden-era income-driven repayment program that offered lower monthly payments and a shorter path to debt relief. President Trump's administration eliminated it, and on July 1, student-loan servicers began sending borrowers formal notices of their 90-day window to transition. Notices are going out in waves; servicers expect every SAVE borrower to receive one by the end of 2026.
The cost of doing nothing
The math is simple. Borrowers who miss their deadline don't get to stay in limbo — they get auto-enrolled in standard repayment. Since the overhaul took effect July 1, borrowers who have already transitioned off SAVE have reported monthly bills that are hundreds of dollars higher, along with errors in payment calculations and difficulty reaching servicers for help.
What to do right now
If you're a SAVE borrower, check your servicer's portal today. Identify your deadline — it may not be September 29 if your notice arrived later. Then compare the remaining income-driven repayment options introduced under the new framework and enroll before your window closes. Don't wait for a second notice; the 90-day clock runs from the date of your first one.
The political backdrop
An ongoing lawsuit is attempting to block the forced transfer of borrowers who don't act voluntarily. Democratic lawmakers, led by Sen. Warren, pushed the Education Department in April to extend the transition window, arguing borrowers need more time and information. The department has held its position. Undersecretary Kent stated the 90-day window gives borrowers 'ample time to explore repayment options that best suit their needs and plan accordingly.'
Scale.'s read
For founders carrying student debt — and there are plenty of you — this is a cash-flow issue, not just a policy story. An unexpected jump of hundreds of dollars a month in loan payments hits runway directly. The SAVE plan's elimination is a legitimate policy debate, but the operational reality is binary: act before your deadline or absorb a payment spike you didn't budget for.
Government-designed auto-enrollment into the most expensive option is a feature of bureaucratic inertia, not an accident. The founders who get this right treat it like any other contract renewal: calendar the deadline, compare the options, and make the decision on your terms — not the servicer's default.